The short answer
A slow-reply revenue estimate should be a sensitivity range built from the business's own verified funnel. Start with unique eligible inquiries, measure response timing consistently, carry records through qualified opportunity, appointment, completed job, invoice, and collected amount, then apply low, base, and high assumptions. Report uncertainty and exclusions beside the result. The number is a decision aid, not a forecast or proof that delay caused the loss.
The dangerous version of a revenue leak calculator is easy to make. Multiply unanswered leads by an average job value, display a large dollar figure, and call the result lost revenue. The arithmetic may be correct while the conclusion is unsupported. Some inquiries are spam. Some are duplicates. Some people are outside the service area. Some never received a message. Some received one and declined. An appointment is not a completed job, an invoice is not collected cash, and revenue is not profit.
The useful version takes more care. It makes each funnel stage inspectable, records where every input came from, and shows how much the output changes when a reasonable assumption moves. That is the purpose of a slow lead response revenue estimate: help an owner decide what to measure or test next without creating false precision.
Begin with the decision, not the biggest possible number
Write one question at the top of the worksheet. Perhaps the owner needs to decide whether to change after-hours coverage, repair a form-to-inbox handoff, or sample old estimates for a consent-aware review. A model built to compare staffing options needs different inputs from one built to diagnose failed message delivery.
Choose one consistent time window and one population. A recent four-week window may be suitable for a current operational check, while a seasonal service may need a comparable period from the prior year. Do not combine annual inquiry volume, a busy-week response rate, and a best-month average ticket. Record the as-of date, systems included, channels covered, owner, and the decision the estimate may inform.
The time window also limits the claim. A model based on one month of plumbing requests says little about roofing demand after a storm or a different branch with another dispatch process. A clear boundary makes the estimate smaller, but much more useful.
Build the denominator from eligible inquiries
Raw form rows and call events are not automatically leads. Create an eligible inquiry set before calculating a missed lead value. Assign a stable review identifier, then document rules for removing test submissions, confirmed spam, duplicates, wrong-party records, existing open jobs when they are outside the question, out-of-service-area requests, and contacts that should not be approached because of consent, suppression, legal, or policy restrictions.
Keep the exclusions as counts with reasons. Do not delete the evidence simply to make the denominator look cleaner. If 12 records cannot be resolved because timestamps are absent, report an unknown group. Moving uncertain rows into the lost column would overstate exposure; moving them into the successful column would hide risk.
GAO's Assessing Data Reliability guide describes reliability in terms of accuracy, completeness, and applicability for the intended purpose. That framing is useful here. A call export can be accurate yet incomplete if it lacks transfers. A CRM can be complete for sales stages yet inapplicable to message delivery. Name those limits before using the data as evidence.
Define what slow and replied mean
A response clock requires two events. The start may be a completed web submission, a connected inbound call that was missed, or delivery of a platform message to an approved inbox. The stop should be a meaningful business response, not an internal assignment, an automated acknowledgement that offers no next step, or an attempted call with no evidence of the result unless the stated metric is specifically first attempt.
Reconcile time zones, daylight saving changes, business hours, overnight inquiries, call transfers, retries, queued integrations, and duplicate notifications. Keep at least two measures when relevant: time to verified attempt and time to customer response. A team can attempt contact quickly while delivery fails. Another team can receive a response after an automated acknowledgement even though no person has reviewed the request.
Response-time groups should be set before looking for the most flattering result. Use operationally meaningful bands and show group sizes. Tiny groups and large amounts of missing data should widen the uncertainty, not produce a stronger claim.
Keep every funnel stage separate
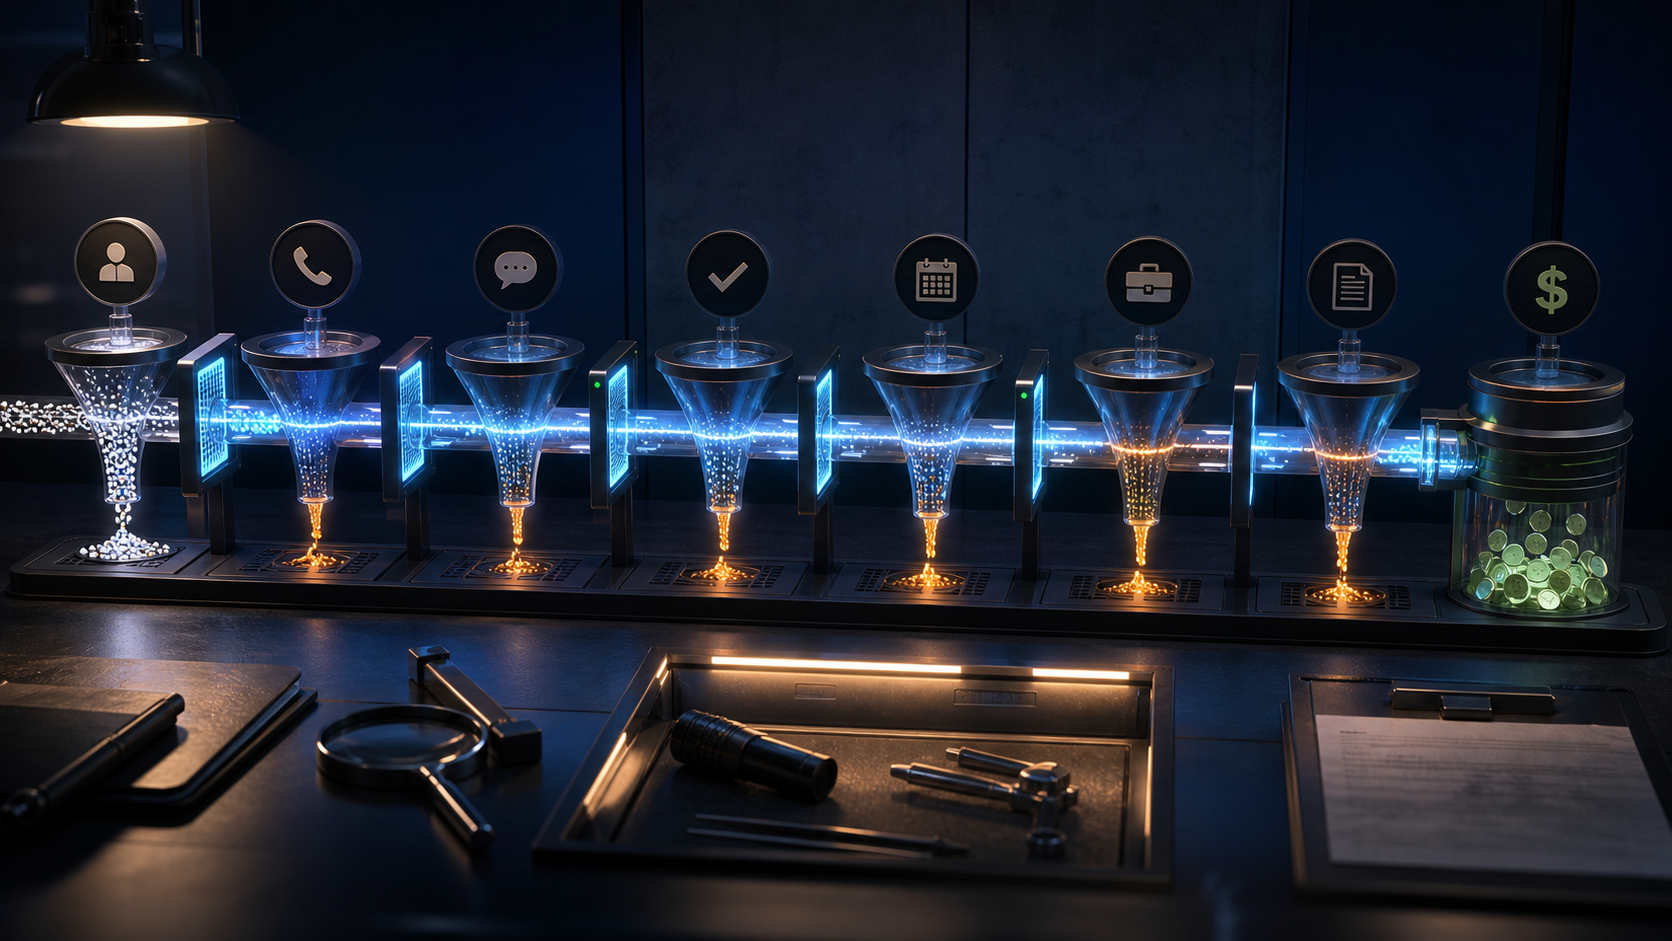
A revenue leak calculator becomes easier to audit when it follows an event ledger rather than one multiplication. A practical chain is: eligible inquiry, verified contact attempt, delivered contact, customer response, qualified opportunity, appointment, completed job, invoice, and collected amount. Your business may need fewer or more stages, but each stage should have a definition and an evidence source.
Google Ads' current offline conversion import guidance explains how first-party offline events can be connected back to earlier online ad interactions. That product-specific documentation does not prove causation or validate a CRM. It does show why later outcomes should be captured as events rather than inferred from the original form fill.
Do not treat every stage as interchangeable:
- Inquiry: someone or something generated an inbound record.
- Qualified opportunity: the business verified fit under a written rule.
- Appointment: a scheduled event exists and its status is known.
- Completed job: the agreed work was recorded as complete.
- Invoice: a charge was issued, which may still be disputed or unpaid.
- Collected amount: payment was received and attributed under the business's accounting method.
If the evidence stops at appointment, the model must stop there or use an explicitly labeled historical range for later stages. It may not quietly assume that every appointment becomes an average job.
Revenue, contribution, profit, and cash answer different questions
Average job value is tempting because it is easy to remember. Check whether it means quoted value, invoiced sales, or collected cash. Gross sales do not deduct the variable costs needed to perform the work. Contribution in dollars is sales less variable costs; the contribution margin ratio divides that difference by sales. What remains must still cover fixed costs before it can become profit. Cash collected is a separate measure and can arrive in a different period.
The U.S. Small Business Administration's break-even guidance uses price minus variable cost to derive contribution margin and warns that assumptions should be grounded in facts. For this model, choose a financial measure that matches the decision. If the question is short-term staffing capacity, contribution may be relevant. If it is cash planning, verified collections may matter more. Label the measure and its source period.
Taxes, refunds, cancellations, warranty work, finance charges, discounts, and uncollected invoices can make quoted or invoiced value diverge from cash. Report them separately when material. Never relabel gross exposure as profit.
Use a range formula that can be challenged
One transparent structure is:
Modeled change in completed jobs = eligible inquiries in the affected group × assumed change in qualification rate × appointment rate among qualified opportunities × completion rate among appointments.
Modeled contribution before fixed costs = modeled change in completed jobs × (sales value per completed job − variable cost per completed job).
Separate cash scenario = modeled change in completed jobs × average net cash collected per completed job over a stated collection window.
Use decimals for the rates. A qualification rate moving from 20% to 25% is a change of 5 percentage points, entered as 0.05, not 0.25. The later rates are conditional on the preceding stage. They are not percentages of all inquiries. Each scenario must use a consistent cohort and financial basis; do not multiply cash collections by a sales-based contribution ratio and call the result accounting profit.
This is a planning model, not a measured treatment effect. It holds the downstream rates constant within each scenario. A change in response handling may also change customer mix, appointment rates, or job size, so that simplification needs testing. With reliable event data, compare complete paths directly. With sparse data, show a wider set of assumptions or stop at an earlier stage. A low, base, and high scenario is not a statistical confidence interval.
Set low, base, and high values from observed business data when it is reliable. Record the period, sample size, channel, service line, and any adjustments. If the business lacks an input, use a clearly labeled test range for planning, not a hidden industry benchmark presented as fact.
A fictional example you can recalculate
Suppose a fictional service office reviews 100 eligible inquiries from one month. It tests qualification-rate changes of 0, 5, and 10 percentage points. For this exercise only, half of qualified opportunities book an appointment and 80% of appointments become completed jobs. Each job has $500 in sales and $300 in variable costs. These are invented inputs, not industry averages or AI Cleanup Doctor customer results.
| Scenario | Qualification change | Modeled extra jobs | Sales | Contribution before fixed costs |
|---|---|---|---|---|
| Low | 0 points | 0 | $0 | $0 |
| Base | 5 points | 2 | $1,000 | $400 |
| High | 10 points | 4 | $2,000 | $800 |
The base calculation is 100 × 0.05 × 0.50 × 0.80 = 2 modeled jobs. Two jobs at $500 give $1,000 in sales; subtracting two lots of $300 leaves $400 in contribution before fixed costs. If net cash collected within the chosen window averages $450 per completed job, the separate base cash scenario is $900. That $900 is not profit and should not replace the $1,000 sales input in the contribution calculation.
Include an adverse case when the evidence permits it. A negative 5-point change produces negative 2 modeled jobs and negative $400 in contribution under the same assumptions. Do not hide this case by forcing every output above zero. Fractional outputs in other scenarios are model averages, not a promise of part of a job.
Check capacity and overlap before using the table. If the office can handle only one additional job, the two-job base case is not feasible without changes and costs. If the same inquiry appears in both a slow-response list and an old-estimate list, count its possible outcome once. Confirm every resulting rate stays between 0% and 100%, and do not add the low, base, and high scenarios together.
Stress the assumptions before acting
Change one input at a time and keep the original calculation beside it. In the fictional base case, reducing the qualification change from 5 points to 2.5 points halves modeled contribution from $400 to $200. Increasing variable cost from $300 to $400 per job also reduces it to $200, for a different reason. Identify which assumption needs better evidence before spending on a response-handling change. If excluding one questionable campaign removes most of the difference, investigate the source mix first.
Comparing fast and slow response groups is descriptive unless the analysis controls for other explanations. Urgent requests may receive faster replies and close more often because they are urgent. High-value jobs may need specialist review and take longer. Season, geography, channel, service type, price, staffing, and lead source can all differ. Report the association and the uncertainty. Do not call the gap caused revenue without a suitable study design.
The FTC's advertising substantiation policy says objective claims require a reasonable basis before dissemination. That boundary applies when a model becomes marketing copy. An internal planning range with clear assumptions is not permission to advertise that a cleanup will recover the displayed amount.
How to build a defensible slow-reply revenue leak estimate
Choose one decision and one time window
State the operational decision the estimate should support, select one comparable period, and record the as-of date. Do not mix monthly inquiry volume with annual revenue or combine campaigns with different customer paths.
Build the eligible inquiry set
Start with unique, in-scope inquiries. Remove documented spam, tests, duplicates, wrong-party contacts, out-of-area requests, suppressed contacts, and records that cannot legally or appropriately be followed up.
Verify the response clock
Define when the clock starts and what counts as a meaningful response. Reconcile timestamps, time zones, business hours, call logs, form events, message delivery, and system delays before grouping records by response time.
Map the full evidence funnel
Count verified contact attempts, delivered contacts, responses, qualified opportunities, appointments, completed jobs, invoices, and collected amounts as separate stages. Preserve an unknown state when the source does not support a stage.
Set low, base, and high assumptions
Use observed business ranges where available and label their source and period. Keep scenario inputs for affected inquiries, conditional stage rates, sales and variable costs. Model cash collections separately, and include zero or adverse cases when appropriate.
Run sensitivity and boundary checks
Change one major assumption at a time, compare response-time groups cautiously, test exclusions, and identify the inputs that move the range most. Do not claim that delay caused every difference without an appropriate causal design.
Issue a decision receipt and measure forward
Record inputs, sources, exclusions, formulas, ranges, limitations, owner, decision, and next measurement date. Use the estimate to choose a bounded test, then compare future verified events rather than presenting the model as guaranteed revenue.
Turn the estimate into a decision receipt
The final page should make review easy. Include the question, period, population, excluded counts and reasons, funnel definitions, source systems, data-quality gaps, financial measure, low, base, and high assumptions, formula, output range, sensitive inputs, limitations, owner, approved action, and next measurement date.
A useful action is narrow: repair one timestamp handoff, add a coverage test for one channel, verify delivery events, or sample one segment of old estimates under the business's contact rules. Keep the old process available for comparison when safe. Measure operational facts such as verified response time and stage completion before attaching a revenue conclusion.
The receipt should also state what the estimate does not show. It does not establish consent, legal authority to contact, causal effect, available fulfillment capacity, customer demand, collection certainty, or profit. Those boundaries protect the owner from acting on a number that the underlying evidence cannot carry.
What a bounded review can do without CRM credentials
An owner can provide a redacted table with stable review IDs, channel, timestamps, response evidence, stage events, exclusion reason, and approved financial ranges. Remove names, complete contact details, messages not needed for the decision, passwords, tokens, payment data, and fields the owner is not authorized to share.
AI Cleanup Doctor can structure the field dictionary, exclusion ledger, funnel table, sensitivity model, limitations, and decision receipt. It cannot establish consent, access private systems without authorization, contact leads, alter live automations, make accounting judgments, or guarantee a result. The authorized owner approves the data, model boundaries, operational test, and any public statement.
Frequently asked questions
What does a revenue leak calculator actually estimate?
It estimates a range of economic value that may be exposed under stated assumptions. It does not prove that slow replies caused every missed outcome or that changing response time will recover the estimated amount.
Should I use average job value or collected cash?
Use the measure that matches the decision and label it precisely. Quoted value, invoiced amount, collected cash, gross revenue, contribution margin, and profit are different measures and should not be substituted for one another.
What records should be excluded from a missed lead value estimate?
Documented spam, tests, duplicates, wrong-party records, out-of-service-area requests, suppressed or no-consent contacts, already active customers when irrelevant, and records with unusable evidence should be excluded or reported separately.
Does a faster reply always cause a higher close rate?
No. Response time can be associated with outcomes, but source quality, service type, urgency, season, price, staffing, geography, and record completeness can also differ. A descriptive calculator should not be presented as causal proof.
Can AI Cleanup Doctor calculate the leak without CRM access?
A bounded review can begin with an owner-approved, redacted event table and financial ranges. The business owner remains responsible for access, lawful contact, live system changes, financial definitions, and any claims made from the result.
Method limits: Sources were rechecked on October 5, 2026. The worksheet and fictional scenarios are our explanation, not a method prescribed or endorsed by these sources. Google Ads documentation describes its own offline conversion features and does not prove causation. GAO supports the data-reliability framing. SBA explains contribution and break-even concepts; an accountant should confirm the business's treatment. FTC policy informs the boundary on objective advertising claims. This guide is not accounting or legal advice. Verify current platform settings, privacy obligations, contact rules, contracts, and applicable law.
The four AI-generated 3D illustrations are conceptual diagrams. They contain no customer records and do not depict actual software screens or measured financial results.
Sources
- Google Ads Help, Your guide to upgrading offline conversion imports. Used for the current product-specific connection between online lead interactions and imported offline events.
- U.S. Government Accountability Office, Assessing Data Reliability. Used for accuracy, completeness, applicability, and risk-based review concepts.
- Federal Trade Commission, Policy Statement Regarding Advertising Substantiation. Used for the reasonable-basis boundary on objective advertising claims.
- U.S. Small Business Administration, Break-even point. Used for the distinction between sales price, variable cost, and contribution margin.